
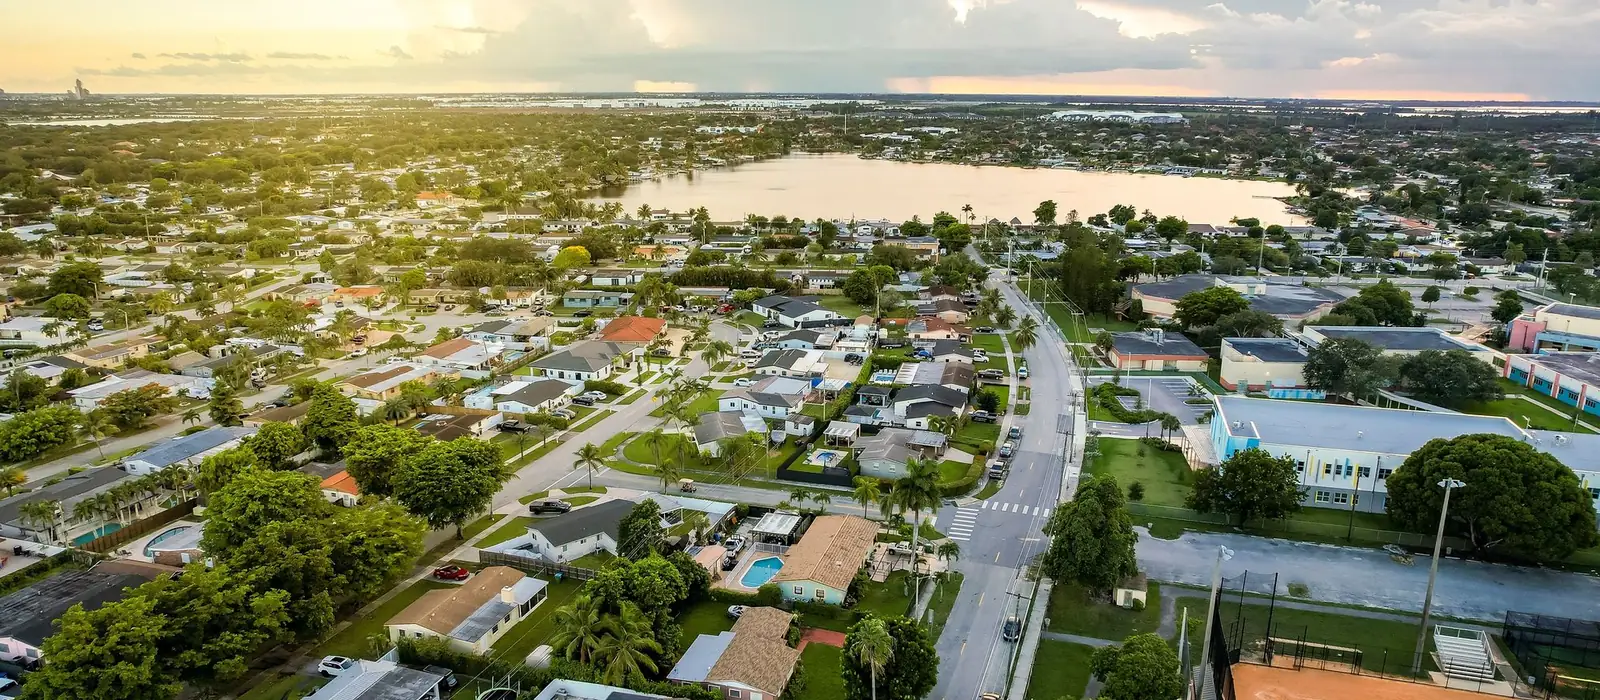
Hialeah, Florida · Miami-Dade County
Hialeah Mortgage Broker
Hialeah homes sell in about six weeks, inventory is tight, and many of the best deals are duplexes or houses with an added unit out back. On Mortgage gets you pre-approved properly, checks what a lender will actually count, and shops your loan across a large wholesale network.
Hialeah’s Mortgage Broker Offering the Lowest Rates
We specialize in Hialeah residential mortgages.
In a market as quick as Hialeah’s, a buyer rarely has time to shop five banks after finding a house. That is the advantage of a wholesale broker. On Mortgage sends your one application to many lenders, compares their rate, points and fees, and has your best options lined up before you write an offer, so you can move as fast as the market does.
Hialeah also rewards picking the right lender, not only the right rate. Many homes here are older concrete block houses that have been expanded over the years, and many buyers are self-employed or earn part of their income in cash-heavy trades. A lender that understands both will get you to closing. One that does not will find problems in week three. We send your file to the first kind.
See what Hialeah buyers are paying today on our Hialeah mortgage rates page, or price your own scenario in the Miami-Dade rate finder.
Hialeah rates from our lenders today
0.162 points
No points, no credit
0.125 points
$672 lender credit
$713 lender credit
Par rate per program for a single-family primary residence in Miami-Dade County, 20% down, 780+ credit, 30-day lock, escrows included. Rates change through the day and are not a commitment to lend. Price your own Hialeah scenario, no credit pull.
On Mortgage: Your Trusted Hialeah Mortgage Broker
On Mortgage arranges tailored mortgage financing for home buyers, investors and property owners throughout Hialeah. As a leading Hialeah mortgage broker, we help clients work through the complexities of this housing market, for first purchases, refinances and rentals alike. We bring the local knowledge and the lender options to secure the best mortgage for your situation.
Hialeah is one of the largest cities in Florida and one of the most densely built in Miami-Dade. Nearly all of its housing is resale, much of it built from the 1950s through the 1980s, and multigenerational households are common, so homes are often larger than they first appear, with family rooms, extra bedrooms and separate units added over the years. That history is part of why buying here takes a broker who knows what lenders will and will not accept.
Hialeah Real Estate Market Insights
As of mid-2026, the median sale price in Hialeah is around $485,000, and homes typically sell in about 45 days, one of the faster paces in South Florida. Low inventory and steady demand from families who want to stay close to Miami keep the market competitive, especially for well-kept single-family homes and duplexes.
Speed changes how you should prepare. Have your pre-approval in hand before you start touring, know your maximum payment including taxes and insurance, and be ready to make a clean offer. Our role as your Hialeah broker is to make your financing as quick and certain as the market requires, because good homes here do not wait.
Additions, efficiencies and what lenders will count
Many Hialeah homes have been expanded over the decades: a converted garage, an enclosed porch, an extra bedroom, or a small apartment with its own entrance rented to a tenant or a relative. Some of that work was permitted. Some was not. It matters, because lenders and appraisers treat the two very differently.
Permitted additions add square footage and value in the appraisal like any other part of the house.
Unpermitted space usually gets little or no value, and an appraiser may flag it for health and safety reasons. A separate unpermitted unit generally cannot be counted as rental income to help you qualify, and in some cases the lender will want it returned to its original use.
Legal duplexes and two- to four-unit properties are different. Rent from a permitted second unit can help you qualify, and if you live in one unit, you may be able to buy with a low down payment through FHA or a conventional owner-occupied loan.
Before you make an offer, ask for the permit history. We will tell you how a lender is likely to view the property.
Investment Property Financing in Hialeah
Hialeah is a strong location for real estate investors. Job growth, a growing population and rising rental demand create good opportunities in rental property, and the city’s central location between Miami, Doral and Miami Lakes keeps tenants coming. Whether you are looking at a duplex, a small apartment building or a commercial property, On Mortgage brings financing options built for investment real estate.
For one- to four-unit properties, conventional investment loans and DSCR loans are the main routes. A DSCR loan qualifies the property on its own rents, so you do not need to show tax returns, and you can close in an LLC. For larger multifamily or mixed-use buildings, which fall under commercial lending, ask us about the options available for your project.
Owner-occupants have a powerful option too: buy a legal duplex, triplex or fourplex, live in one unit and rent the others. FHA allows 3.5% down on two- to four-unit owner-occupied properties, and the projected rent from the other units can help you qualify. Learn more about investor financing on our DSCR loans page.
Hialeah homeowners insurance and property taxes
Hialeah pays the same county-level premiums as the rest of Miami-Dade, which rank near the top statewide, and the age of many homes adds to the challenge. A roof replaced in the last decade, updated electrical and plumbing, and hurricane shutters or impact windows can bring a quote down considerably. Sitting west of the bay keeps Hialeah out of surge zones, though a few low streets are mapped for flooding. Here is the escrow on a homesteaded home at the Hialeah median price.
Sources: Florida county homeowners insurance premiums (worthinsurance.com) and county total millage (movewithmomentum.com), updated October 2026. Your own premium depends on the home’s age, roof, construction and wind mitigation features, and flood coverage is a separate policy. Property tax and homeowners insurance are estimates (1.2% and 0.85% of the home’s value per year). Your actual taxes and insurance premium depend on the property, exemptions and the policy you choose, and will be confirmed on your Loan Estimate. Run your own numbers.
Hialeah Housing Market Forecast for 2026 and Beyond
The Hialeah housing market is expected to keep moving upward, with home prices forecast to rise about 3% over the coming year. Its location next to Miami, its low inventory and steady demand keep Hialeah competitive, and with very little land left to build on, that pressure is unlikely to ease soon. New development on the city’s western edge adds some supply, but most buyers will keep competing for existing homes.
As your trusted Hialeah mortgage broker, On Mortgage helps you secure the most competitive rates whether you are buying, refinancing or investing. Homeowners with equity built up over the last several years can use a cash-out refinance to permit an addition properly, replace a roof or buy a second property.
Why Choose On Mortgage as Your Hialeah Mortgage Broker?
Hialeah buyers need a broker who moves quickly, understands older homes and knows how to document real income. OnMortgage offers:
- FHA loans for single-family homes and owner-occupied duplexes
- Conventional loans from 3% down
- VA loans for veterans
- Bank statement loans for business owners and tradespeople
- DSCR loans for rental properties
- Jumbo loans for larger homes and multi-unit properties
- Refinancing and cash-out
Also looking at West Hialeah, Doral or Miami? See every city on our areas we serve page.
Our Reviews
What Florida borrowers say after closing with On Mortgage. Five stars on Google (130 reviews) and Zillow (92 reviews).
“Caroline Da Silva from Miami Mortgage Brokers just got us approved for our first mortgage, and we would definitely work with her again after this experience! From the moment our broker connected us with Caroline, she was always several steps ahead throughout the process. We were impressed that Miami Mortgage Brokers had us clear to close a week early,...”
“Chris was outstanding throughout the entire transaction! Always accessible and was able to provide the best financing option when others could not! I would highly recommend him and hope to do more transactions with him.”
“I recently had the pleasure of working with Chris as my loan officer, and I cannot speak highly enough of his exceptional service. He guided me through every step with clarity and patience. What truly sets Chris apart is his remarkable efficiency: not only was he incredibly responsive to my inquiries, but he also expedited the loan process, resulting in the...”
Hialeah mortgage broker: your questions
Can I get a mortgage on a Hialeah home with an unpermitted addition?
Often, yes, but the unpermitted space will usually get little or no value in the appraisal, and the appraiser may require safety issues to be fixed. A separate unpermitted unit generally cannot count as rental income. Check the permit history before you offer, and we will tell you how a lender is likely to treat it.
Can I buy a duplex in Hialeah with FHA?
Yes. FHA allows you to buy a two- to four-unit property with 3.5% down if you live in one of the units. Rent from the other units, based on leases or the appraiser’s estimate, can help you qualify. The units must be legal, and the property must meet FHA standards.
How fast do I need to be in Hialeah’s market?
Homes typically sell in about 45 days, and well-priced homes often go much faster. Have underwriting-ready paperwork before the first showing, settle on a payment ceiling that includes taxes and insurance, and plan to write an offer within a day of seeing the right house. We can usually turn around a pre-approval letter quickly once your documents are in.
Can self-employed buyers get a mortgage in Hialeah?
Yes. If your tax returns show enough income, a conventional or FHA loan works. If deductions reduce it, a bank statement loan can qualify you using 12 or 24 months of deposits. Keep business and personal funds clearly documented, and avoid large unexplained cash deposits before you apply.
How much is homeowners insurance in Hialeah?
Miami-Dade County’s average premium, shown on this page, is among the highest in Florida. Your quote depends mostly on the roof’s age, the electrical and plumbing, and wind protection. A four-point and wind mitigation inspection can help you find discounts. We get quotes started during your inspection period.
Why use a Hialeah mortgage broker instead of a bank?
Banks offer their own programs and can be strict with older homes, multi-unit properties and self-employed income. A broker compares many lenders and finds the one whose guidelines fit both you and the property, at a competitive price. You also get one consultant managing the process from application to closing.
More for Hialeah borrowers
Nearby in Miami-Dade
Contact OnMortgage: Hialeah’s Leading Mortgage Broker
Whether it is your first home, a duplex you will live in, or your next rental, our brokers will compare lenders and help you move quickly in Hialeah’s fast market. Get a free quote today.