
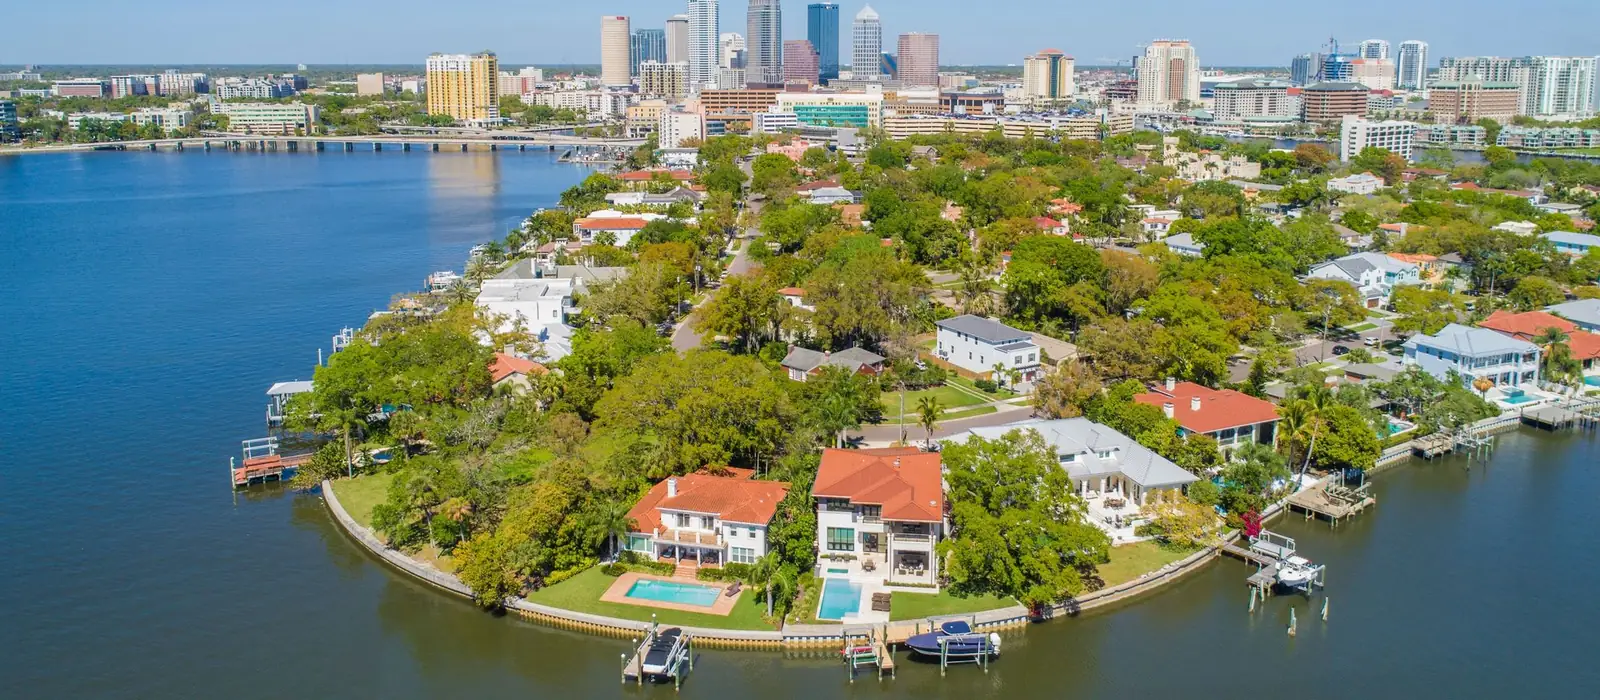
Hillsborough County · Tampa Bay
Tampa Mortgage Broker
Tampa moves quickly, and the right loan depends on whether you are relocating for a job downtown, buying near MacDill, stepping into your first home in Seminole Heights or adding a rental to your portfolio. We shop each of those across many wholesale lenders and keep one consultant on your file from offer to keys.
Tampa's Mortgage Broker Offering the Lowest Rates
We specialize in Tampa residential mortgages.
The lowest rate in Tampa is rarely sitting at the bank where you already have a checking account. Each lender sets its own pricing every morning, and the spread between the best and the average on the same borrower can be wide enough to change your monthly payment by a meaningful amount. As a wholesale mortgage broker, On Mortgage puts your scenario in front of many lenders at once and shows you the results side by side, with the points or lender credit for each option spelled out.
The other half of the job is getting it closed. Our loan consultants are not order takers working from one product sheet. They know which lenders move fastest in underwriting, which ones handle self-employed income cleanly, and which ones are comfortable with the older homes and flood-zone properties that are common around Tampa Bay. That knowledge is what keeps a 30-day closing on schedule.
See the result for yourself on our Tampa mortgage rates page, priced live for Hillsborough County, or explore FHA loans in Tampa if a low down payment matters more than anything else.
Tampa’s Premier Mortgage Broker: On Mortgage
On Mortgage is proud to serve Tampa, a vibrant Gulf Coast city known for its thriving economy, its cultural diversity and a real estate market that keeps drawing new residents. Whether you are buying your first home, upgrading to a luxury property or investing, we build the financing around your situation.
Relocating to Tampa
Buyers moving in for jobs in finance, healthcare, tech and the port often need to close on a timeline set by a start date. We can pre-approve you before you arrive and lock a rate for the closing date.
Military families near MacDill
Active-duty and veteran buyers can use VA loans with no down payment and no monthly mortgage insurance, in South Tampa and across the county.
First-time buyers
FHA with 3.5% down, conventional with as little as 3%, and zero-down options for qualified buyers in neighborhoods like Seminole Heights and Sulphur Springs.
Investors
Long-term rentals near downtown, USF and the suburbs, financed on the property’s rent with a DSCR loan, no tax returns required.
What our lenders are pricing in Hillsborough County today
No points, no credit
0.125 points
0.162 points
$672 lender credit
$713 lender credit
Par rate per program for a single-family primary residence in Hillsborough County, 20% down, 780+ credit, 30-day lock, escrows included. Rates change through the day and are not a commitment to lend. Price your own Tampa scenario, no credit pull.
Explore Tampa’s Housing Market
As of mid-2026, the median sale price in Tampa is around $440,000, and homes typically sell in about 41 days. That is a faster market than much of South Florida, so it pays to have financing settled before you tour. A full pre-approval, with income and assets reviewed, carries more weight with Tampa sellers than a quick pre-qualification. As your local Tampa mortgage broker, On Mortgage matches you with financing built around how this market actually moves.
Price and loan type follow the neighborhood. This is how financing tends to line up across the city:
| Area | What is typical | Financing that usually fits |
|---|---|---|
| South Tampa, Hyde Park, Davis Islands | Older and renovated single-family homes, waterfront and near-water lots, higher price points | Conventional and jumbo; flood coverage often required in low-lying blocks |
| Seminole Heights, Tampa Heights, Sulphur Springs | Bungalows and renovated older homes, a strong first-time buyer market | FHA, low-down conventional, renovation financing |
| Channelside, Water Street, Downtown | High-rise and mid-rise condos | Conventional in warrantable buildings, portfolio loans where a building is non-warrantable |
| Westchase, New Tampa | Newer suburban single-family homes, HOA communities, strong schools | Conventional and VA; HOA dues built into the payment |
| Ybor City and East Tampa | Townhomes, infill new construction and small multifamily | Conventional, FHA, and DSCR for investors |
Homeowners insurance and property taxes in Tampa
Insurance became the line Tampa buyers ask about first after the 2024 storm season, when Helene’s surge and Milton’s winds hit Tampa Bay within weeks of each other. Premiums in Hillsborough County are still well below the South Florida counties, but they vary sharply by the home’s age, its roof and whether it sits in a flood zone. Here is what the county numbers look like on a home at Tampa’s median price. A newer roof and documented wind mitigation features (impact windows, hurricane straps, a secondary water barrier) can bring a quote well under the average, and an older home may need a four-point inspection before a carrier will write it.
Sources: Florida county homeowners insurance premiums (worthinsurance.com) and county total millage (movewithmomentum.com), updated October 2026. Your own premium depends on the home’s age, roof, construction and wind mitigation features, and flood coverage is a separate policy. Property tax and homeowners insurance are estimates (1.2% and 0.85% of the home’s value per year). Your actual taxes and insurance premium depend on the property, exemptions and the policy you choose, and will be confirmed on your Loan Estimate. Run your own numbers.
Tampa: A Hotspot for Real Estate Investors
A growing population and a strong job market make Tampa one of the most consistent rental markets in Florida. New residents keep arriving faster than new housing can be built, which supports demand for long-term rentals across the city and its suburbs. On Mortgage specializes in financing investment properties so your portfolio works in a competitive market.
Most Tampa investors we work with fall into two groups. Some are buying their first rental and qualify with conventional investment-property financing, usually with 15% to 25% down. Others already own several properties, hold them in an LLC or have tax returns that understate their cash flow, and for them a DSCR loan qualifies the purchase on the property’s rent instead. Both are priced across our lender panel so the numbers work from the first month.
The Future of Tampa Real Estate
Tampa’s housing market is projected to keep growing steadily, with home values expected to rise about 5% over the next year. New infrastructure projects, well-regarded schools and a lively cultural scene all add to the city’s pull, and the downtown and Water Street redevelopment keeps bringing new employers and residents into the urban core.
For buyers, steady appreciation is an argument for not waiting indefinitely for a perfect rate: you can buy now and refinance later if rates fall, while the home builds equity in the meantime. For owners, rising values open up cash-out refinancing for renovations, debt consolidation or a down payment on a rental. As your trusted Tampa mortgage broker, we make sure you are positioned for both.
Why Choose On Mortgage as Your Tampa Mortgage Broker?
The right broker gives you more lenders, more programs and one person accountable for your closing. At OnMortgage we offer the full range of Tampa home financing:
- Conventional mortgages for primary residences, second homes and investment property
- FHA loans with low down payments and flexible credit
- VA loans for veterans and the MacDill community
- Jumbo loans for luxury properties in South Tampa, Davis Islands and Bayshore
- Refinancing solutions, from rate reductions to cash-out
- Bank statement loans for business owners
Our brokers understand what makes the Tampa market different, from flood-zone underwriting to fast-moving offers, and work to secure the best terms whether you are a first-time buyer or an experienced investor.
From first call to closing
- See real pricingRun your scenario on the Tampa rate finder, no credit pull, or call us.
- Get fully pre-approvedWe review income and assets up front so your offer carries weight in a 41-day market.
- Line up insurance earlyWe help you get wind and, where needed, flood quotes during the inspection period.
- Lock and closeYour consultant manages underwriting, appraisal and the title company through to the closing table.
Our Reviews
What Florida borrowers say after closing with On Mortgage. Five stars on Google (130 reviews) and Zillow (92 reviews).
“We cannot say enough amazing things about Caroline! As a first-time homebuyer, this was such a huge and exciting milestone for us, and we’re so grateful that we had her by our side throughout the entire process. Caroline was incredibly knowledgeable, patient, responsive, and supportive from beginning to end.”
“I had an amazing experience working with Ms. Caroline Da Silva throughout my entire home-buying process. From day one, she was professional, knowledgeable, responsive, and always there whenever I had questions. She kept me updated every step of the way and made everything easy to understand.”
“Caroline was great. Always responsive and available whenever I needed assistance or had questions. 10/10 would recommend to any veteran or anyone for that matter.”
Tampa mortgage broker questions
What is the benefit of using a mortgage broker in Tampa?
A broker prices your loan across many wholesale lenders instead of one bank’s rate sheet, which usually means a lower rate or lower costs for the same borrower. We also match your file to a lender whose guidelines fit it, which matters for self-employed income, condos and flood-zone homes, and we manage the loan through closing.
Do I need flood insurance to buy a home in Tampa?
Only if the home is in a FEMA Special Flood Hazard Area and you are using a mortgage, in which case the lender requires it. Large parts of South Tampa, Davis Islands and the bayfront fall in those zones. Many buyers outside the zones choose to carry it anyway after 2024. We check the flood zone early so your payment estimate includes it if needed.
How much do I need to put down on a house in Tampa?
As little as 3% on many conventional loans, 3.5% with FHA, and nothing with a VA loan if you are eligible. Investment properties usually need 15% to 25%. On a home near the Tampa median, the difference between those options is large, so we show them side by side with the full monthly payment.
How fast can you close a Tampa home purchase?
Most Tampa purchases close in about 30 days from an accepted offer, and faster is possible when the appraisal and insurance come together quickly. Getting fully pre-approved before you make offers, and getting your insurance quote during the inspection period, are the two things that keep a closing on time.
Can I buy a rental property in Tampa without showing tax returns?
Yes. A DSCR loan qualifies the purchase on the property’s expected rent compared with its payment, so your personal income and tax returns are not used. Down payments are typically 20% to 25%, and the loan can close in an LLC.
Are Tampa homeowners insurance rates going down?
Florida’s market has stabilized as new carriers have entered and the 2022 and 2023 reforms took effect, but Tampa premiums remain sensitive to roof age, construction and flood exposure. The county average above is a starting point. A wind mitigation inspection on the home you are buying is the single best way to bring your own quote down.
More for Tampa borrowers
Nearby in Tampa Bay
Contact OnMortgage: Tampa’s Leading Mortgage Broker
Ready to buy or refinance in Tampa? Talk with a broker who prices your loan across many lenders and stays with your file until it closes. Personal service, honest numbers, and a plan built around your timeline.