
Home / Florida / Fort Lauderdale
Broward County · Venice of America
Fort Lauderdale Mortgage Broker
Canal-front homes, beach condos, historic bungalows and inland starter homes each need a different lender in Fort Lauderdale. On Mortgage is the local broker that knows which one, and shops your loan across a large wholesale network to find it.
See Live Florida Mortgage Rates And Closing Costs!
No points, no credit
0.125 points
0.162 points
$672 lender credit
$713 lender credit
Choose your option on the full rate page, purchase, refinance or cash-out, and see Broward County rates upon completion. Price your own Fort Lauderdale scenario, no credit pull.
Your Local Fort Lauderdale Mortgage Broker
Home loans built for the Fort Lauderdale market.
If you are searching for a mortgage broker in Fort Lauderdale, FL, you want more than a rate quote. You want someone who understands Broward County, from waterfront estates on the Las Olas Isles to condos along the beach and starter homes inland. On Mortgage is a local Fort Lauderdale mortgage broker. Instead of pushing one bank’s products, we compare rates and programs across a large network of wholesale lenders to find the loan that actually fits your purchase.
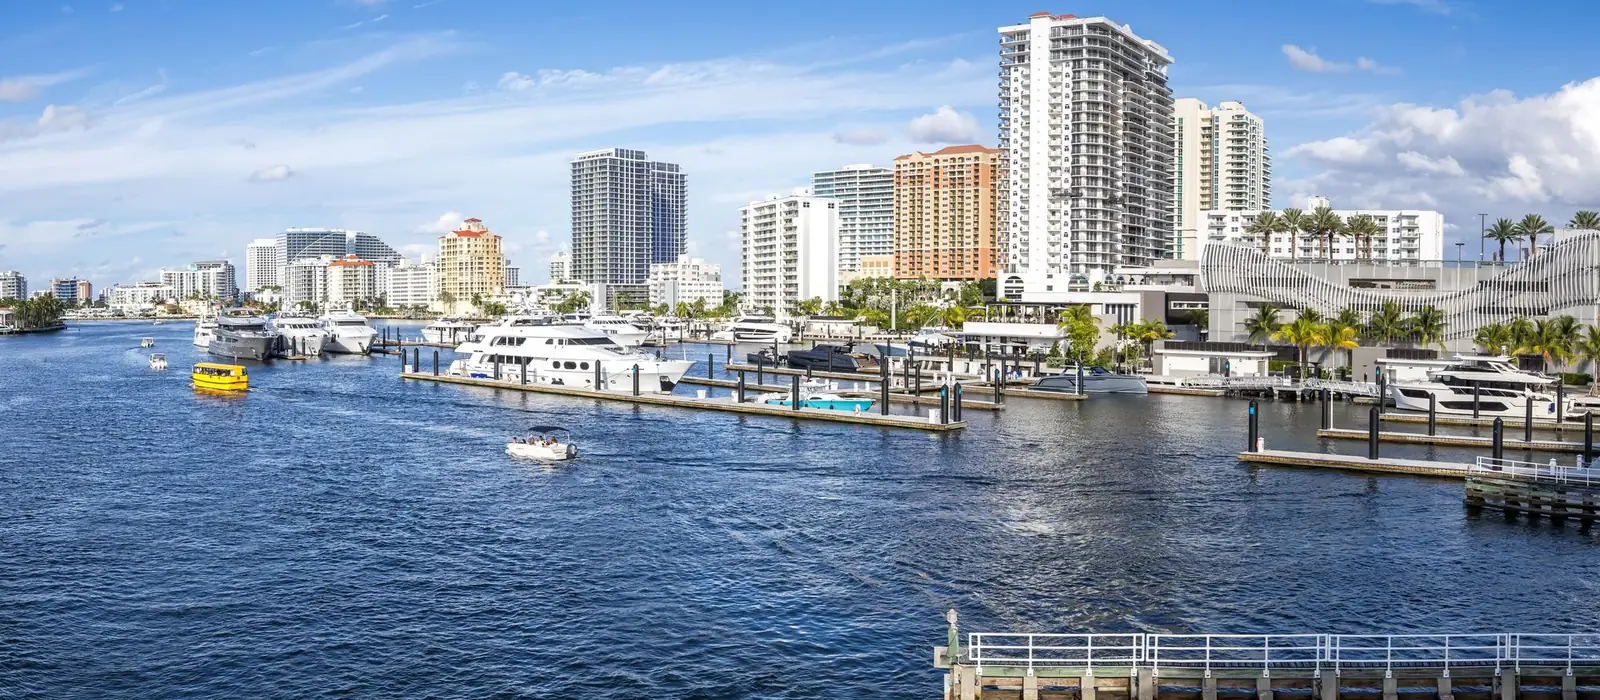
Fort Lauderdale is a city built on water, with so many miles of canals and waterways that it carries the nickname Venice of America, and the water shapes the mortgage more than buyers expect. It sets the price of the home, the cost of the insurance, whether flood coverage is required and, for condos, how the building has handled its reserves and inspections. A good broker sorts all of that out before you are under contract rather than after the appraisal.
Check today’s Fort Lauderdale mortgage rates with Broward taxes and insurance included, or start your application and talk to a consultant who works this market every day.
Why Use a Local Fort Lauderdale Mortgage Broker
Broward County has quirks a national call center will not know. A local broker does.
Financing a home in Fort Lauderdale is not the same as financing one in the middle of the country. Homeowners and flood insurance cost more near the coast, many of the best properties are waterfront or condos with their own lending rules, and Broward County has its own conforming loan limit that decides where a jumbo loan begins. The mortgage brokers at On Mortgage live and work in this market, so we match your loan to a lender that is comfortable with Fort Lauderdale property, its insurance realities and its condo and HOA requirements. That local knowledge is the difference between a smooth closing and a deal that falls apart at the last minute.
Insurance is part of approval
Lenders qualify you on the full payment, insurance included, and Broward premiums are among the highest in Florida. A quote that arrives late can push your ratios over the line. We get wind and flood quotes started the week your offer is accepted.
Flood risk is not only on the map
The April 2023 rainstorm flooded Fort Lauderdale neighborhoods that sit outside high-risk zones. Flood insurance is only required in a mapped zone, but we price it on every quote so the choice is yours with real numbers.
Waterfront appraisals are their own craft
Canal width, ocean access, bridge clearance and seawall condition all move value on the water. We order through appraisers who know Broward waterfront, which protects your loan amount on a jumbo purchase.
Fort Lauderdale Neighborhoods We Serve
From the water to the suburbs, we help buyers finance homes across the city and beyond.
Las Olas Isles & Rio Vista
Waterfront and luxury. Deep-water lots off Las Olas Boulevard and along the New River, where most purchases are jumbo loans and buyers often hold assets rather than W-2 income. Asset-depletion and bank statement programs are common here, along with the larger reserve requirements that come with a high loan amount.
Victoria Park & Colee Hammock
Historic in-town living. Older homes and newer infill a few minutes from downtown. Many sit in flood zones and have older roofs, so the insurance quote and the four-point inspection deserve attention early. Conventional loans with 10% to 20% down are typical.
Coral Ridge & Harbor Beach
Canal-front homes. Coral Ridge has miles of navigable canals, and Harbor Beach sits on a private beach near Port Everglades. Expect elevation certificates, flood policies and jumbo pricing, and expect a lender to look closely at seawall and dock condition in the appraisal.
Sailboat Bend & Tarpon River
Character homes near downtown. Older homes on the river with historic district rules in Sailboat Bend. Renovation financing can make sense for a buyer who wants to update, and FHA and conventional both work for well-kept homes.
Wilton Manors & Oakland Park
Walkable and central. Smaller single-family homes, townhomes and villas, with strong demand from first-time and move-up buyers. FHA and conventional loans with 3% to 5% down fit well, and villas and townhomes with an HOA need the same association review as a condo.
Beachfront condos
Along A1A and the Intracoastal. From Galt Ocean Mile to the high-rises south of Sunrise Boulevard, the building decides the loan. Warrantable buildings get conventional pricing. Buildings with high investor ratios, open litigation or large assessments need a portfolio lender, which we place every week.
We also serve the surrounding Broward County markets, including Hollywood, Pompano Beach, Pembroke Pines, Plantation, Davie and Sunrise. Every city we cover is on our areas we serve page.
Buying a Fort Lauderdale condo after Florida’s new condo laws
After the Surfside collapse in 2021, Florida passed laws requiring milestone structural inspections for condo buildings three stories and taller, structural integrity reserve studies, and properly funded reserves for roofs, structure and other major components. Many older buildings along the beach and the Intracoastal have been catching up, and some have passed large special assessments to do it.
Lenders now look harder at condo questionnaires, and Fannie Mae and Freddie Mac will not buy loans in buildings with unresolved critical repairs. That does not make a Fort Lauderdale condo hard to finance. It makes it important to know the building before you write the offer.
Loan Programs for Fort Lauderdale Buyers
Whatever you are buying in Fort Lauderdale, we broker a loan that fits it:
- Conventional loans for primary homes, second homes and rentals, with as little as 3% down for first-time buyers and mortgage insurance that cancels as you build equity.
- FHA loans with 3.5% down at a 580 credit score and flexible ratios, useful in a county where insurance raises the payment. FHA condos must be on the approved list.
- VA loans for veterans and service members, with no down payment and no monthly mortgage insurance.
- Jumbo loans above the Broward County conforming limit, for waterfront, canal-front and luxury condo purchases.
- DSCR investor loans that qualify a rental on its own rent, with no tax returns and LLC closings allowed.
- Bank-statement loans for business owners, boat captains, realtors and other self-employed buyers whose tax returns do not tell the full story.
Already own? A refinance can lower your rate or pull cash out for a new roof, impact windows or a seawall repair, and those upgrades often lower your insurance too. The refinance calculator shows how long the savings take to cover the closing costs.
The Fort Lauderdale Housing Market
Fort Lauderdale remains one of South Florida’s most desirable markets, driven by its beaches, its boating lifestyle and a steady flow of buyers relocating from higher-tax states. Waterfront and Intracoastal properties command a premium, the condo market is deep and active, and demand for both primary homes and investment properties stays strong. Port Everglades, the airport, the marine industry, healthcare and a growing downtown office and residential core keep jobs in the city as well.
That mix makes financing here specialized. A waterfront jumbo, a beach condo and an inland starter home each call for a different lender and loan. Condo buyers have more choice and more leverage than they did a few years ago, especially in older buildings working through their reserve requirements, while well-maintained single-family homes on the water remain in short supply. As your Fort Lauderdale mortgage broker, we position your loan with the lender best suited to the property you are actually buying, and we build the full payment, insurance and HOA included, before you make the offer.
Mortgage Companies in Fort Lauderdale: Broker vs. Bank
There are plenty of mortgage companies in Fort Lauderdale, but they are not all the same. A bank or a single-source mortgage company can only offer its own loans, so if your file does not fit that one box, your options end there. As an independent mortgage broker in Fort Lauderdale, On Mortgage is not tied to any single lender. We compare rate, fees, turn times and guidelines across our full network and bring you the strongest option, which is especially valuable on the waterfront homes, condos and self-employed borrowers that Fort Lauderdale is full of.
| The question | Bank or retail lender | On Mortgage, independent broker |
|---|---|---|
| Whose rates do you see? | One lender’s rate sheet | Many wholesale lenders, compared side by side |
| Building not warrantable? | Usually the end of the conversation | Portfolio and non-QM lenders that finance it |
| Self-employed or asset-rich? | Tax returns, often only tax returns | Bank statement, asset depletion, DSCR and full-doc options |
| Pricing on a jumbo? | Fixed by that bank’s appetite that month | Shopped across jumbo lenders that are actively competing |
| Who answers the phone? | Often a different department at each stage | One consultant from pre-approval to keys |
Prefer a broader look first? See our home loan broker and Florida mortgage broker pages.
What insurance and taxes add to a Fort Lauderdale payment
Broward County’s average homeowners insurance premium is among the highest in Florida, close to double the statewide average, and that number belongs in your budget from the first day you look at homes. The county figure is an average across all homes; a newer concrete home with impact windows and a recent roof can come in far below it, while an older home near the water can come in above it. The example below uses a $500,000 home as an illustration, not a median price. Flood insurance is extra, required in a mapped flood zone and worth pricing everywhere east of US-1.
Condo owners carry a smaller HO-6 policy because the association insures the structure, but the master policy cost shows up in the HOA dues instead.
Sources: Florida county homeowners insurance premiums (worthinsurance.com) and county total millage (movewithmomentum.com), updated October 2026. Your own premium depends on the home’s age, roof, construction and wind mitigation features, and flood coverage is a separate policy. Property tax and homeowners insurance are estimates (1.2% and 0.85% of the home’s value per year). Your actual taxes and insurance premium depend on the property, exemptions and the policy you choose, and will be confirmed on your Loan Estimate. Run your own numbers.
Our Reviews
What Florida borrowers say after closing with On Mortgage. Five stars on Google (130 reviews) and Zillow (92 reviews).
“I am a first time home buyer, so all of this was new to me. Caroline helped me every step of the way. I’m so grateful, because of her it was possible to own this house that I am so excited to create into my home. I would definitely work with you again for any future business.”
“We cannot say enough amazing things about Caroline! As a first-time homebuyer, this was such a huge and exciting milestone for us, and we’re so grateful that we had her by our side throughout the entire process. Caroline was incredibly knowledgeable, patient, responsive, and supportive from beginning to end.”
“Caroline was great. Always responsive and available whenever I needed assistance or had questions. 10/10 would recommend to any veteran or anyone for that matter.”
Fort Lauderdale Mortgage Broker FAQs
Why use a Fort Lauderdale mortgage broker instead of a bank?
A bank offers only its own loans. A Fort Lauderdale mortgage broker shops many lenders on your behalf, which matters here because Broward County financing often involves waterfront homes, condos and higher insurance costs that some lenders handle far better than others. You also keep one consultant on your file, rather than being handed between departments.
Can you finance condos in Fort Lauderdale?
Yes. Condo financing is one of the trickiest parts of this market because lenders review the building’s warrantability, reserves, insurance and, since Florida’s new condo laws, its milestone inspection and reserve study. As a broker we know which lenders approve which buildings, which saves you time and failed applications. Non-warrantable buildings go to portfolio lenders we work with regularly.
What loan programs do Fort Lauderdale buyers use most?
Conventional and FHA loans for primary residences, jumbo loans for waterfront and luxury homes, VA loans for veterans, and DSCR loans for investors buying rentals. Self-employed buyers often use bank statement loans. We broker all of them and will show you which costs less on your specific purchase.
Do you serve all of Broward County?
Yes. Beyond Fort Lauderdale we serve Hollywood, Pompano Beach, Pembroke Pines, Plantation, Davie, Sunrise, Coral Springs, Weston, Miramar and the rest of Broward County. We are licensed throughout Florida, so we also finance homes in Palm Beach and Miami-Dade counties for buyers comparing areas.
Do I need flood insurance in Fort Lauderdale?
Your lender requires flood insurance only if the home is in a FEMA special flood hazard area, such as an A or V zone. Much of the city near the water is. Outside those zones it is optional, but heavy rain has flooded Fort Lauderdale neighborhoods outside the mapped areas, and preferred-risk policies can be inexpensive. We price it on every quote so you can decide.
What happens if my condo building has a special assessment?
It depends on the size of the assessment and whether it is already being paid. Lenders review assessments through the condo questionnaire, and a large unpaid assessment for critical repairs can make a building ineligible for conventional financing until the work is done. Sometimes a seller pays it off at closing. We review the documents early so you know where you stand.
More for Fort Lauderdale borrowers
Nearby in Broward
Talk to a Fort Lauderdale Mortgage Broker Today
Ready to see your best rate on a Fort Lauderdale home? Contact On Mortgage for a free, no-obligation quote and let us compare lenders for you.