
Home / Florida / St. Petersburg
St. Petersburg · DSCR loans for older homes
DSCR Loans for St Petersburg Investment Properties
Rental financing for St. Petersburg bungalows, block homes and small multifamily that qualifies on rent, with the roof, often the cheapest way to raise the ratio, priced out.
St Petersburg DSCR Loan Overview
If you are an investor looking for a DSCR loan in St Petersburg, this financing option allows you to qualify based on property cash flow rather than personal income.
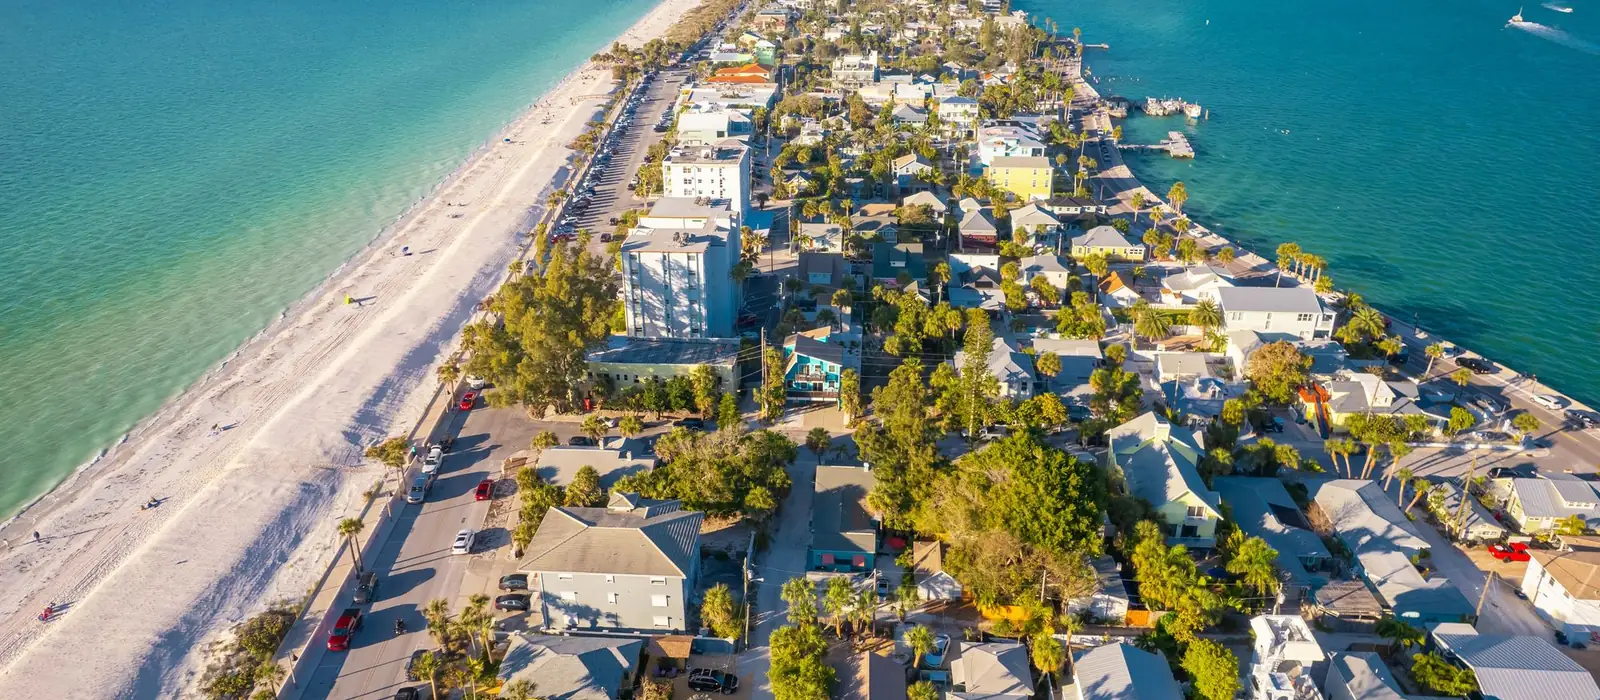
Much of St. Petersburg was built between the 1920s and the 1960s: craftsman bungalows in Kenwood and Old Northeast, block houses in the neighborhoods north and west of downtown, and small duplexes and fourplexes throughout. Those homes rent well to the people who make the city work, from hospital staff at Bayfront and Johns Hopkins All Children’s to restaurant and arts workers downtown.
Older homes carry older roofs, and since Florida’s insurance market tightened, the roof has become one of the biggest drivers of a rental’s carrying cost. After the 2024 hurricanes, insurers have looked even harder at roof age and condition. A DSCR loan qualifies on rent against the full payment, insurance included, so a roof can make or break the ratio. Buying a home for yourself? See St. Petersburg mortgage rates.
Why Saint Petersburg Is a Strong Market for DSCR Loans (2025 to 2026)
Renter Occupancy Share
The 2019 to 2023 ACS puts owner occupancy at 63.0 percent, implying about 37.0 percent of housing is rented. Demand is strongest in the walkable neighborhoods near downtown and along Central Avenue.
Measured Rent Levels
Early 2026 averages: around $1,827 for a one-bedroom and $2,213 for a two-bedroom. Updated three-bedroom bungalows lease in the mid-$2,000s and up; unrenovated homes trail that.
Income Profile and Rental Stability
Median household income was about $73,118 over 2019 to 2023. A growing professional base and steady service employment keep well-kept rentals occupied.
Understanding DSCR Loans for St Petersburg Investors
A lender computes DSCR by dividing monthly rent by PITIA, which stands for principal, interest, taxes, insurance and association dues. In older St. Petersburg homes, the “I” can swing by hundreds of dollars a month depending on the roof, the electrical panel, plumbing type and whether a wind mitigation inspection documents storm-resistant features.
A new roof does three things for a rental: it opens access to more insurance carriers, it can earn wind mitigation credits (roof deck attachment, roof-to-wall connections, secondary water barrier, and hip roof shape where applicable), and it removes a large repair from your near-term budget. For a DSCR file, the first two lower PITIA directly.
If you are buying, the inspection and the insurance quote should come before the end of your inspection period, so a roof credit or price reduction can be negotiated with real numbers.
A St Petersburg DSCR Example
A 1950s three-bedroom block home outside the flood zone, $390,000 with 25% down, renting for $2,500. With its 20-year-old shingle roof, the only available policy costs well above the county norm. After a $20,000 roof replacement and a wind mitigation inspection, the premium falls below it. Premiums are illustrations.
| $390,000, rent $2,500 | Original roof | New roof, wind credits |
|---|---|---|
| Landlord insurance, monthly | $445 | $238 |
| PITIA | $2,930 | $2,724 |
| DSCR | 0.85 | 0.92 |
| Roof cost | None yet | $20,000 |
| Insurance saved per year | None | $2,478 |
| Years for the savings to repay the roof | Not applicable | 8.1 |
| Extra down payment for the same DSCR gain | About $28,824 more down would lower the payment by the same amount | |
Insurance starts from Pinellas County’s average homeowner premium for this value plus about 15% for rental use, then is raised 40% for the old roof and lowered 25% for the new one as illustrations; real quotes vary by carrier and house. Tax $390 a month at Pinellas’ average millage, no homestead. Rate 7.750%, a sample DSCR rate (homeowner par plus a point).
The roof lifts the ratio as much as roughly $28,824 of extra down payment would, for a fraction of the cash, and it keeps paying back every year in lower premiums. On a purchase, the better move is often to negotiate the roof into the price: a seller credit or price reduction, with the roof replaced right after closing or before, so the policy is written on the new roof. On a refinance, replacing the roof first and then applying with the new premium can turn a declined file into an approved one.
St Petersburg DSCR Calculator
- Loan amount
- $292,500
- Principal and interest
- $2,096
- Full payment (PITIA)
- $2,803
- Rent needed for 1.00
- $2,803
- Rent needed for 1.25
- $3,504
Preset to the block home above with a county-average landlord premium. Enter your actual insurance quote for the real ratio.
Today’s Pinellas County ratesHow DSCR loans workMore mortgage calculators
DSCR Financing for Investment Properties in St Petersburg
For an older St. Petersburg rental, line these up before you commit:
- Roof age and permit history from the city’s records
- A four-point inspection and a wind mitigation inspection
- Actual insurance and flood quotes on the house
- Repair and permit history from any 2024 storm damage
- Leases and rent history if the home is occupied
We compare DSCR lenders and help structure purchase credits so the loan is underwritten on the best insurance the house can get. For owner-occupied loans, see our St. Petersburg mortgage broker page.
DSCR Loan FAQs for St Petersburg Investors
What is a DSCR loan?
An investment property loan that checks whether the home’s rent pays its mortgage, taxes, insurance and dues, rather than checking your paycheck or tax return.
Can I get a DSCR loan on a home with an old roof?
Possibly, if you can obtain insurance. Many carriers will not insure older roofs, and the policies that will cost more, which lowers the ratio. Some lenders also flag roofs near the end of their life.
Does a new roof lower insurance in St. Petersburg?
Usually. It broadens carrier choice and can qualify for wind mitigation credits, especially with documented roof deck attachment and roof-to-wall connections.
Can the seller pay for the roof?
Often through a price reduction or a credit within lender limits. Credits generally go toward closing costs, so a price reduction is the more common route for large repairs.
Is flood insurance required?
If the home is in a high-risk flood zone, lenders require it, and the premium goes into PITIA. Many St. Petersburg neighborhoods near the water are in such zones.
What ratio do I need?
Most lenders want at least 1.00 for standard terms. Older homes with high insurance often need more down or a lower-ratio program.
Our Reviews
What Florida borrowers say after closing with On Mortgage. Five stars on Google (130 reviews) and Zillow (92 reviews).
“We cannot say enough amazing things about Caroline! As a first-time homebuyer, this was such a huge and exciting milestone for us, and we’re so grateful that we had her by our side throughout the entire process. Caroline was incredibly knowledgeable, patient, responsive, and supportive from beginning to end.”
“I had an amazing experience working with Ms. Caroline Da Silva throughout my entire home-buying process. From day one, she was professional, knowledgeable, responsive, and always there whenever I had questions. She kept me updated every step of the way and made everything easy to understand.”
“Caroline was great. Always responsive and available whenever I needed assistance or had questions. 10/10 would recommend to any veteran or anyone for that matter.”
More for St. Petersburg borrowers
Nearby in Tampa Bay
Price the roof into your St. Petersburg rental
Send the address, roof age and any insurance quotes. On Mortgage will run the ratio both ways, help structure a credit and compare DSCR lenders.