
Home / Florida / St. Petersburg
Live Pinellas County pricing · updated 11/9/2026
St. Petersburg Mortgage Rates
Waterfront and downtown St. Pete financing, with flood-zone expertise built in. Purchase and refinance rates are live below, along with the math that tells you whether a refinance actually pays.
Today’s St. Petersburg Mortgage Rates
0.125 points
No points, no credit
$374 lender credit
$672 lender credit
$1,577 lender credit
Par rate per program for a single-family primary residence in Pinellas County, 20% down, 780+ credit, 30-day lock, escrows included. Rates change through the day and are not a commitment to lend. Price your own St. Petersburg scenario, no credit pull.
St. Petersburg refinance rates today
$531 lender credit
No points, no credit
$374 lender credit
$672 lender credit
0.049 points
Rate-and-term refinance pricing for a Pinellas County single-family primary residence with 20% equity and excellent credit. Cash-out, condo and investment refinances price differently; see the break-even table below. Price your own St. Petersburg scenario, no credit pull.
St. Petersburg Mortgage Rates Today: Financing a Walkable Waterfront City
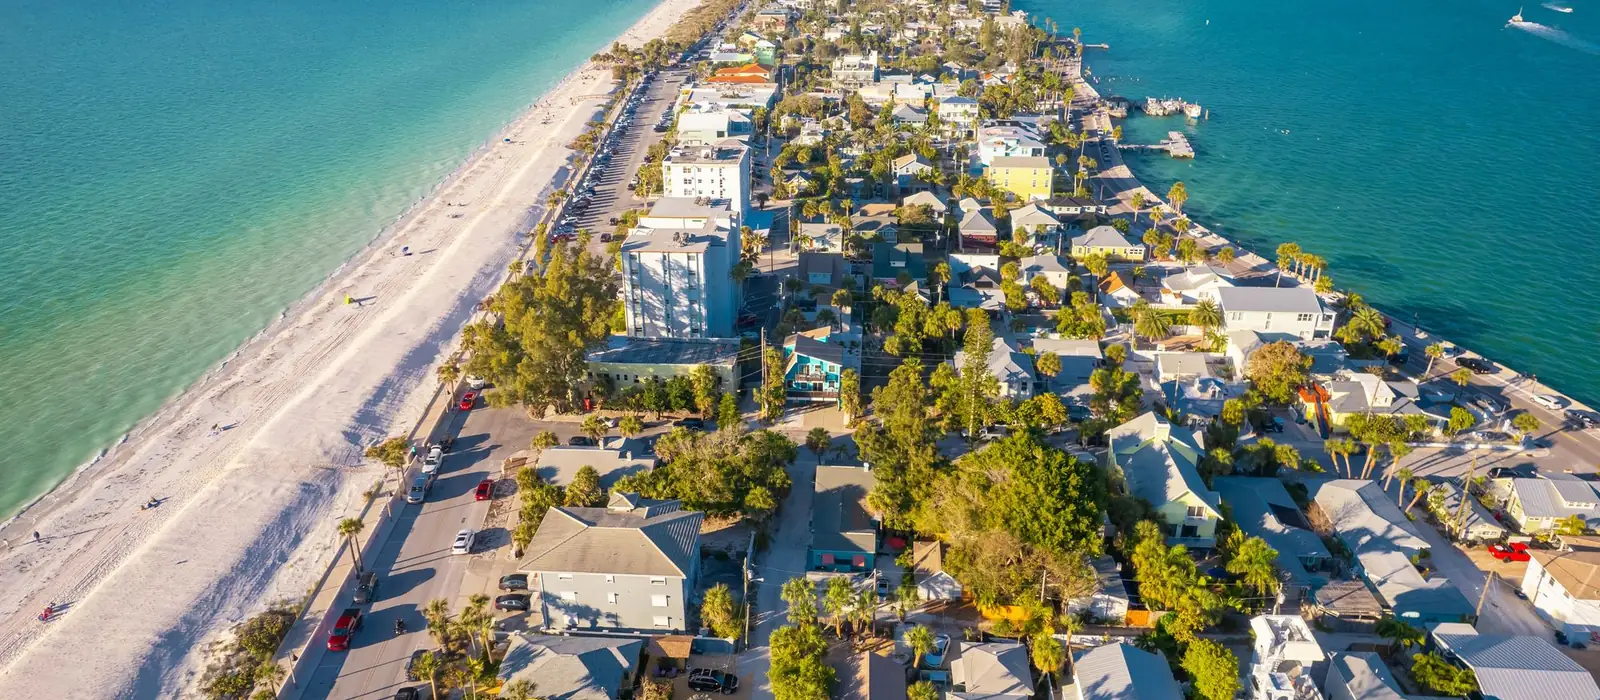
St. Pete’s walkable downtown, its museums and murals, and miles of waterfront parks have pushed typical home prices into the mid $400,000s, drawing first-time buyers, relocators, retirees and luxury waterfront buyers alike. Inventory has grown since the 2024 hurricanes, and buyers now have more choice and more room to negotiate.
Today’s par 30-year fixed for a Pinellas County purchase is 6.625% with 20% down and strong credit; for waterfront homes above the conforming limit, our jumbo panel’s 30-year is at 6.375%.
From the bungalows of Historic Kenwood and Old Northeast to the waterfront streets of Snell Isle, On Mortgage prices your loan across multiple lenders to secure the strongest rate for your scenario, with flood and wind insurance priced in from the start.
Does a St. Petersburg refinance pay? The break-even math
A refinance makes sense when the monthly savings repay the closing costs well before you expect to move or refinance again. Here is that calculation for a $340,000 balance, a new 30-year loan at today’s par 30-year fixed for Pinellas County, and an illustrative $5,500 in closing costs:
| Your current rate | Current principal and interest* | New payment at 6.625% | Monthly change | Break-even |
|---|---|---|---|---|
| 7.875% | $2,465 | $2,177 | $288 saved | 20 months |
| 7.500% | $2,377 | $2,177 | $200 saved | 28 months |
| 7.125% | $2,291 | $2,177 | $114 saved | 49 months |
| 6.875% | $2,234 | $2,177 | $57 saved | 98 months |
*Payment on the same balance over a fresh 30-year term, so the comparison isolates the rate. If you are several years into your current loan, restarting at 30 years also lowers the payment by stretching the term, which is not a true saving; ask us to compare on your remaining term. Par pricing; a lender credit can reduce or eliminate the closing costs at a slightly higher rate.
Want to pay nothing out of pocket? The live ladder below shows today’s refinance rates from points to lender credit on the same balance. A credit large enough to cover your costs means the break-even is immediate, at the price of a slightly higher rate.
| Rate on a $340,000 loan | APR | Points cost or lender credit | Payment vs. par | Points pay back in |
|---|---|---|---|---|
| 6.375% | 6.443% | You receive $425 | Same | Not applicable |
| 6.500% | 6.521% | You receive $2,125 | $28/mo more | Not applicable |
| 6.625% | 6.625% | You receive $2,975 | $56/mo more | Not applicable |
| 6.750% | 6.750% | You receive $5,100 | $84/mo more | Not applicable |
| 6.875% | 6.875% | You receive $6,800 | $112/mo more | Not applicable |
Rate-and-term refinance pricing for a Pinellas County primary residence at 75% loan-to-value, 30-year fixed, 30-day lock.
Flood Zones & Waterfront Financing in Snell Isle & Shore Acres
A large share of St. Petersburg sits in FEMA AE and VE flood zones, including sought-after areas like Snell Isle, Shore Acres, Venetian Isles and Coquina Key, where flood insurance is mandatory on federally backed loans. Hurricane Helene’s surge in September 2024 flooded many of these neighborhoods, and buyers and lenders now look closely at each home’s elevation and flood history.
Those flood premiums, plus windstorm costs, feed directly into your qualifying ratios. On Mortgage prices real flood and wind insurance into your pre-approval and lines up lenders comfortable with coastal and waterfront collateral, including jumbo lenders for Snell Isle and Old Northeast homes above the conforming limit, so your closing holds together.
AE zones
High-risk areas with a defined base flood elevation. Homes built or raised above it insure for much less.
VE zones
Coastal areas exposed to wave action, with stricter construction standards and the highest premiums.
The 50% rule
If repairs or improvements exceed half the building’s value, the home must be brought up to current flood standards. Ask about any substantial damage determination.
Condo & Refinance Options in Downtown St. Pete
Downtown’s condo towers are popular, but Florida’s condo safety laws, updated again in 2025, require structural inspections and reserve studies for older buildings, and the resulting special assessments can affect financing. Lenders review the association’s budget, reserves and insurance. On Mortgage vets condo warrantability before you fall in love with a unit, and finds portfolio lenders for buildings that do not meet agency rules.
Existing owners can refinance to lower a rate, drop mortgage insurance once equity reaches 20%, or tap equity. A cash-out refinance is also a common way to pay for Helene repairs not fully covered by insurance, or for elevation and storm hardening that cuts future premiums. Explore FHA options in St. Petersburg, connect with a St. Petersburg mortgage broker, or run numbers in the refinance calculator.
St. Petersburg homeowners insurance and property taxes
Pinellas carries the highest average homeowners premium in the Tampa Bay area and one of Florida’s higher county millage rates. Here is the escrow on a homesteaded single-family home at the typical St. Pete price, before flood insurance, which many homes here also need.
Sources: Florida county homeowners insurance premiums (worthinsurance.com) and county total millage (movewithmomentum.com), updated October 2026. Your own premium depends on the home’s age, roof, construction and wind mitigation features, and flood coverage is a separate policy. Property tax and homeowners insurance are estimates (1.2% and 0.85% of the home’s value per year). Your actual taxes and insurance premium depend on the property, exemptions and the policy you choose, and will be confirmed on your Loan Estimate. Run your own numbers.
Neighborhoods we serve
Downtown and the waterfront
High-rise and mid-rise condos near the pier and parks, where building finances and warrantability shape the loan.
Old Northeast and Snell Isle
Historic homes and waterfront estates, often jumbo, with flood zones on the lower streets.
Historic Kenwood and Crescent Lake
1920s bungalows on higher ground, popular with first-time buyers using conventional, FHA and VA loans.
Shore Acres, Venetian Isles and Coquina Key
Waterfront and canal homes where elevation, flood history and insurance quotes come first.
Our Reviews
What Florida borrowers say after closing with On Mortgage. Five stars on Google (130 reviews) and Zillow (92 reviews).
“We cannot say enough amazing things about Caroline! As a first-time homebuyer, this was such a huge and exciting milestone for us, and we’re so grateful that we had her by our side throughout the entire process. Caroline was incredibly knowledgeable, patient, responsive, and supportive from beginning to end.”
“I had an amazing experience working with Ms. Caroline Da Silva throughout my entire home-buying process. From day one, she was professional, knowledgeable, responsive, and always there whenever I had questions. She kept me updated every step of the way and made everything easy to understand.”
“Caroline was great. Always responsive and available whenever I needed assistance or had questions. 10/10 would recommend to any veteran or anyone for that matter.”
St. Petersburg Mortgage Rates: Frequently Asked Questions
What are today's St. Petersburg mortgage rates?
Current St. Pete purchase and refinance rates are shown live at the top of this page. Your rate depends on your loan amount, home value and credit tier, and your payment also depends on whether the property sits in a flood zone that requires additional insurance.
Do I need flood insurance in St. Petersburg?
Often, yes. A large share of St. Pete, including Snell Isle, Shore Acres and Venetian Isles, sits in FEMA AE or VE flood zones where flood insurance is mandatory on federally backed loans. Premiums depend on the individual home’s elevation and features. We price this into your pre-approval up front.
Can you finance waterfront homes in St. Pete?
Yes. On Mortgage works with conforming and jumbo lenders comfortable with coastal and waterfront collateral, and we plan for the flood and windstorm insurance that comes with it, as well as seawall and dock condition.
Is it hard to finance a downtown St. Pete condo?
It depends on the building. Florida’s condo laws require inspections and reserve funding for older buildings, and special assessments or pending repairs can affect warrantability. We check the building before you commit, and use portfolio lenders when agency financing is not available.
Can I refinance my St. Petersburg home?
Yes, whether you want to lower your rate, drop mortgage insurance or take cash out for repairs or upgrades. The break-even table above shows when a lower rate repays its costs, and we will run the same numbers on your actual loan.
More for St. Petersburg borrowers
Nearby in Tampa Bay
Get your St. Petersburg rate quote
Buying, refinancing or taking cash out for repairs, On Mortgage will price your St. Pete loan across many lenders, with flood and insurance costs included. Call or start a quote today.